Emergency Fund vs Investing: What Should Come First?
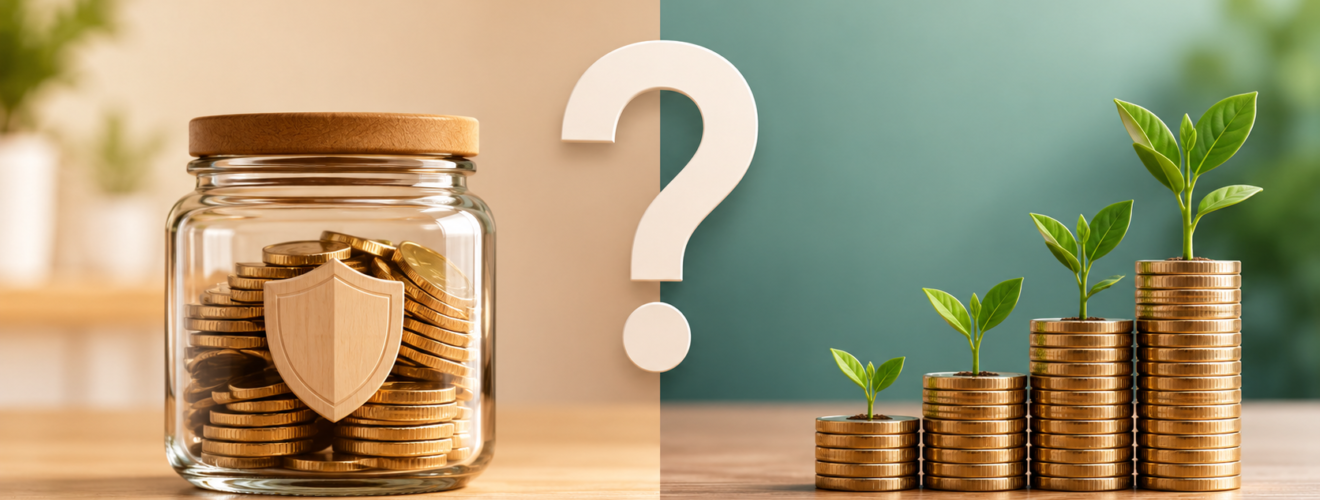
Many people face the same money question: should they build an emergency fund first, or should they start investing as soon as possible?
Both goals matter. An emergency fund gives you cash for sudden costs. Investments can help your money grow over many years. The challenge comes when you do not have enough money to do both at the same time.
The right choice depends on your income, monthly costs, debt, job stability, family needs, and the time you have before you need the money.
The main idea remains simple. Money for an emergency needs safety and easy access. Money for long-term goals can take more market risk because you may not need it for many years.
What Is an Emergency Fund?
An emergency fund is money kept aside for sudden and important costs. It can help you deal with a job loss, medical bill, urgent home repair, major car expense, or another serious need.
This money has a different purpose from your investments. You should not depend on stocks or other assets for an urgent expense because their value can fall at the exact time you need cash.
A common target is three to six months of essential expenses. Fidelity’s September 2026 guidance suggests that people can start with $1,000 and then work toward three to six months of essential expenses.
Some people may need a larger amount. A person with an unstable income, dependents, or other higher risks may need more cash than someone with a very stable job and few financial responsibilities.
In India, NISM also uses three to six months of household expenses as a general emergency-fund guide. In some situations, six to twelve months may make more sense.
The important point is that the number is not the same for everyone.
Why an Emergency Fund Comes First for Many People
An emergency can arrive without warning. Your income may stop, or a large expense may appear at the wrong time.
Without cash set aside, you may have to use a credit card, take a loan, borrow from family, or sell an investment.
Selling an investment during a market fall can create a second problem. You may have to sell at a loss instead of giving the investment time to recover.
This is one reason Schwab’s recent guidance highlights the value of a cash reserve. An emergency fund can reduce the need to sell investments during a poor market period.
A cash reserve can also reduce financial stress. When you know that essential expenses can be covered for several months, a sudden income problem may become easier to manage.
Does This Mean You Should Never Invest First?
No. The answer is not always as simple as “save six months of expenses, then invest.”
There can be good reasons to invest while you build your emergency fund.
For example, if your employer offers a retirement contribution match, it may make sense to contribute enough to receive the full match. Otherwise, you may miss out on a benefit that forms part of your compensation.
Your personal situation also matters. Someone with a very stable income, strong job security, low costs, and family support may have a different cash requirement from someone with a variable income and several dependents.
So, an emergency fund should not become an excuse to delay long-term wealth building for many years.
The Role of High-Interest Debt
Debt adds another layer to this decision.
If you have expensive debt, such as high-interest credit card debt, putting every extra dollar into investments may not be the best use of your money.
A practical approach can involve a small emergency cushion first. You can then focus more money on expensive debt while you continue to build your cash reserve.
Once costly debt is under control and you have a suitable emergency fund, more of your spare cash can go toward long-term investments.
The exact order depends on the interest rate, debt size, income stability, and your ability to handle an unexpected expense.
How Much Should You Keep in Cash?
Three to six months of essential expenses remains a useful starting point.
The key word is “essential.” You do not need to calculate the amount from every expense you make each month.
Think about rent or a home payment, food, utilities, insurance, transport, debt payments, basic medical costs, and other necessary bills.
For example, if your essential monthly costs are $2,000, three months would equal $6,000. Six months would equal $12,000.
A person with a secure job may feel comfortable near the lower end of that range. A person with an unstable income may prefer a larger reserve.
NISM’s guidance in India also points to three to six months of household expenses, with six to twelve months possible in some cases.
There is no universal number that works for every household.
Where Should Emergency Money Stay?
Emergency money needs two main qualities: safety and access.
A savings account is one common option because you can usually access the money quickly. In the United States, high-yield savings accounts have offered rates around 4% or more in 2026, although rates can change as market conditions change.
This makes cash reserves somewhat more useful than they were during periods when savings rates were close to zero.
For people in India, options can include a savings account or other suitable cash products. Recent Indian financial guidance has also discussed sweep-in fixed deposits and debt funds as possible choices, with focus on liquidity and stability rather than simply chasing the highest return.
The purpose of an emergency fund is not to produce the highest possible return.
Its purpose is to be there when you need it.
Why You Should Separate Short-Term and Long-Term Money
One of the easiest ways to understand this subject is to give each part of your money a clear job.
Cash for an emergency has a short-term job. It must remain available and stable.
Money for retirement may have a job that lasts twenty or thirty years. It can usually handle more price movement because you have more time before you need it.
Vanguard’s June 2026 research takes this idea further. Its guidance suggests that cash can also cover expenses expected over about the next year. This approach can help people keep money for near-term needs outside the market while they leave longer-term money invested.
This is not about choosing cash over investments. It is about matching the type of money with the time when you may need it.
What About People With Irregular Income?
People with variable income may need a larger emergency fund.
A salaried employee with a stable job may have a lower risk of sudden income loss. A freelancer, business owner, commission-based worker, or contractor may face larger income swings.
That does not mean every self-employed person needs twelve months of expenses in cash. It means income stability should form part of the decision.
A larger cash reserve can provide more protection when monthly income is hard to predict.
It may also reduce the chance that you need to sell investments or take expensive debt during a weak income period.
What If You Have No Emergency Fund?
If you have no emergency savings at all, the first goal can be a small cash buffer.
Fidelity’s September 2026 guidance suggests starting with $1,000 before working toward a larger reserve.
The exact first target can depend on your circumstances. Someone with very low expenses may need less for the first stage, while someone with high essential costs may need more.
The purpose of the first step is to create some protection from small financial shocks.
After that, you can work toward three to six months of essential expenses.
What If You Already Have Three to Six Months Saved?
Once you have a suitable emergency reserve, the balance can shift toward long-term goals.
At this stage, money that you do not expect to need for many years can have a different role.
You may consider retirement accounts, diversified investments, or other long-term assets that fit your goals and risk level.
The emergency fund can remain separate. This makes it easier to know which money is available for emergencies and which money has a long-term purpose.
You also do not need to stop adding to your emergency fund forever. You can review it when your income, expenses, family situation, debt, or financial goals change.
What About Money You Need Within One Year?
Money that you expect to need within about a year generally has a different role from retirement money.
If you know that you will need the money soon for a major expense, market risk may create a problem. A market fall just before you need the cash could reduce the amount available.
Vanguard’s 2026 research highlights the value of a broader cash strategy for near-term expenses.
This does not mean every dollar needed within twelve months must sit in the same type of account. It means the time horizon should matter when you choose where to keep the money.
A Simple Way to Think About the Order
The process can be easier when you divide your money into three groups.
The first group is for emergencies. This money should focus on safety and access.
The second group is for near-term needs. This money is for expenses you expect within a relatively short period.
The third group is for long-term goals. This money can usually accept more market movement because you have more time.
This approach removes much of the confusion around the emergency fund versus investing question.
You do not have to choose one forever.
You give each dollar a job based on when you may need it.
The Bottom Line
For many people, an emergency fund should come before aggressive long-term investing. A reserve of three to six months of essential expenses is a widely used target, while people with less stable income or greater financial responsibilities may need six to twelve months.
At the same time, “emergency fund first” does not mean you must avoid all investing until you reach a perfect number. An employer retirement match, manageable debt, stable income, and other personal factors can change the order.
The most useful rule is simple: keep emergency money safe and easy to access, and give long-term money enough time to grow.
Your emergency fund protects you from the unexpected. Your investments help you prepare for the future. A strong financial plan gives both jobs instead of asking one to do the work of the other.
Also Read – How to Read a Company’s Cash Flow Statement